CRA proposed rollbacks could mean roadblocks for community development
Recently proposed rollbacks to the CRA would weaken bank obligations to invest, lend, and provide services to low and moderate-income communities. These rollbacks would be roadblocks to positive, impactful community development.
Block by Block is a solutions journalism series that is supported by CEDAM, Invest Detroit and MI CDFI, and is focused on community development leaders and initiatives in Michigan, Ohio and Indiana.
Every year, banks, CDFIs, philanthropic and financial institutions work together to invest in their communities. Together, they’re able to build new homes, health care centers, open up new businesses, daycares and schools — creating healthy, sustainable neighborhoods.
In part, some of this investment was made possible from the Community Reinvestment Act. Since 2010, the (CRA) has helped drive nearly $5 trillion in mortgages and small business loans, strengthening neighborhoods and entrepreneurs across the country. The CRA was passed in 1977 in order to end discriminatory redlining — requiring banks to meet the credit needs of the communities they serve.
Recently, the Office of the Comptroller of the Currency (OCC) and the Federal Deposit Insurance Corporation (FDIC) proposed a new change, calling for rollbacks. These new proposed rules could weaken bank obligations to invest, lend, and provide services to low and moderate-income communities.
If these proposed rollbacks did occur, certain banks would no longer have to invest in affordable housing, small businesses, workforce development, community healthcare, education — negatively impacting their community development. The impact across sectors would be critical.
The National Community Reinvestment Coalition (NCRC) is a network of almost 800 organizations across the country working to champion for a Just Economy. They work with community leaders, policymakers, and institutions to strengthen low-wealth communities, train and represent community organizations, advancing equitable opportunities, advising, investing in enterprises, and holding public and private institutions accountable.
Kevin Hill is a senior policy advisor at the NCRC.
“We are a nationwide network of largely nonprofit organizations and advocacy organizations that work to make sure our financial system treats people fairly,” he says. “We are very interested in the CRA and similar policies that make it so that banks have to invest and serve all communities in a safe and sound way.”
The NCRC published a bulleted story on the proposed 2026 CRA rollbacks, key takeaways, and why it matters.
The story dives into the proposal, which would:
-use the courts to narrow CRA and restrict future modernization,
-eliminate or weaken CRA requirements for hundreds of banks by raising asset thresholds,
-create a low community development benchmark that could be 85% less than current industry standard,
-put thousands of branches in underserved communities at greater risk,
-put affordable housing and community development investment and financing at risk – especially in smaller markets,
-undermine the financial health of unbanked and underbanked communities,
-change the definition of economic development by removing its focus on working-class people and communities,
-expand CRA credit for infrastructure projects without requiring substantial benefits for working-class people or communities.
The proposal also would:
-allow banks to use their strategic plan to do significantly less for communities,
-make CRA easier to game by narrowing what gets examined and broadening what gets credit,
-hides lending gaps and makes banks harder to hold accountable,
-restrict CRA credit for grants that pay basic nonprofit operating costs.
Hill says the CRA serves as a companion to The Fair Housing Act, The Equal Credit Opportunity Act, and the Home Mortgage Disclosure Act.
“There’s something that those laws didn’t do, and that is what the CRA does — establish that the banks have to show that they’re not only not discriminating, but that they are proactively trying to serve all communities where they operate,” Hill says.
To ensure banks are serving their communities, each bank is examined by one of three different government agencies: the OCC for nationally-chartered banks, the FDIC for state-chartered banks, or the Federal Reserve for state-chartered member banks. Those regulatory agencies examine banks to see how they’re lending to borrowers with low to moderate-incomes, in low to moderate census tracts or neighborhoods, and small businesses.
“Currently, for all banks above $412 million in assets, they will also have a community development evaluation — which will look at how well they are financing things like affordable housing, economic development, workforce development, health services, education, and schools,” Hill says.
Today, the regulations for how those banks are being evaluated are proposed being updated, the first significant update since 1995. The past three Administrations have tried to update the CRA regulations, but the current Administration is attempting to rollback CRA requirements.
“They’re basically trying to raise asset thresholds, which determine how banks are evaluated — how much they’re evaluated on,” Hill says. “They want to excuse over 800 banks across the country from any form of community development, and want to put another 400 banks currently in the large category and put them into the intermediate category.”
Hill argues that this would be a pretty significant change. The NCRC published a story showing that the CRA’s new benchmark could put 85% of current community development at risk.
“Through the rulemaking process, the agencies are signaling to the banks that they can do much less for communities than they’re currently doing, and we will continue to pass you,” he says. “That’s not something we can accept or afford as a country right now. I also think it shows the agencies are trying to make the law as weak as possible through this regulatory effort. We would argue that this would go against how Congress wanted the CRA to work.”
Instead of the money which used to be required to invest towards things like hospitals, schools, housing, etc., banks could use that money to serve other banks or large corporations instead.
Emily Reyst is the director of external affairs at CEDAM, a nonprofit membership trade organization with more than 300 members across the state. CEDAM was one of many organizations that wrote a letter to the FDIC sharing its comments on calling for a modernization to CRA which strengthen — rather than weaken, bank accountability for meeting the credit needs of low- and moderate-income communities.
“This is not new, we’ve seen CRA proposed changes before,” Reyst says. “This time though, it does feel a bit scarier in terms of what might be the outcome here. We are potentially expecting some intense litigation around implementation if the proposal is adopted.”
Reyst says the proposed changes would impact organizations like CEDAM, its partners, and the public.
“We rely heavily on investment from CRA incentivized entities, including banks,” she says. “There’s some research that shows in Michigan, if the proposal were to go through — that 15 of 64 banks would lose any community development obligation at all. We’re talking about economic development initiatives, supporting community services in underserved communities, grantmaking, investment in these critical entities that support their communities — they would be at risk of losing funding.”
The changes would have a profound impact on housing in a state that’s already experiencing a housing crisis.
“If you’re a renter, you will find it harder to find affordable rental housing in your community,” Hill says. “Right now, for banks that have to do community development, many of them do that through affordable housing — loans to construct more apartment buildings or rehab apartment buildings. When that goes away, there’s going to be less supply for affordable housing, which is going to make the rents increase.”
“When we zoom in specifically to affordable housing, if we reduce the obligation that banks have to invest in affordable housing, we’ll see not only less investors in the game, but there will be less demand for those tax credits.” Reyst says. “Even for the projects that do find investment, they’ll likely find an even bigger financial gap in getting their projects done. The impact could be really dire in terms of the affordable housing landscape in this country.”
Byna Elliott is the President and CEO of OppFund, Michigan’s only CDFI loan offering single-family mortgage loans. Their mission is to provide loans to create equitable economic and sustainable opportunities to Michiganders — one person, one job, one home at a time.
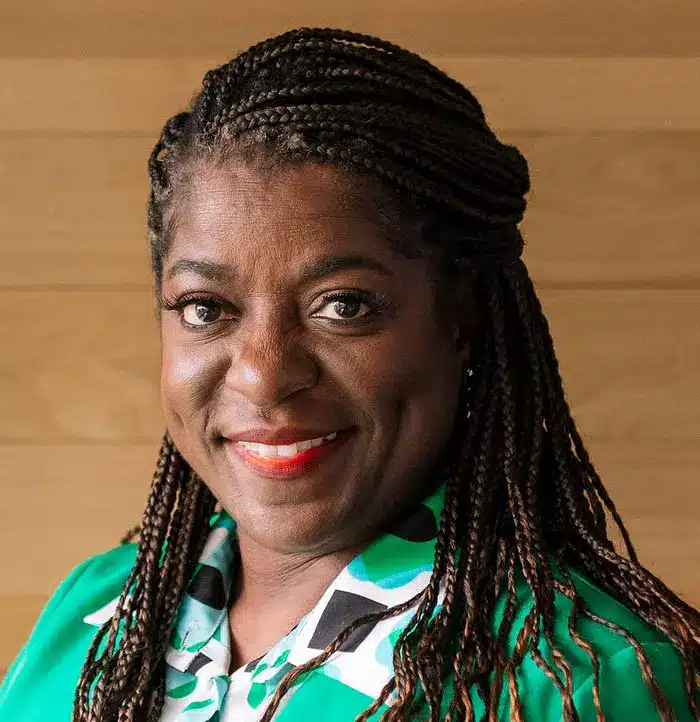
Elliott’s background covers access to capital as an OCC bank examiner, a banking executive in community reinvestment work, and in her current role.
“My understanding of why this matters started on Detroit’s eastside, near Gratiot, where I grew up,” she says. “My mother became a first-time homebuyer at the young age of 60 with help from a homeownership program. So when I talk about opportunity, I see my mother and families like ours.”
In the Gratiot/7 Mile area, 78% of residents classified as low- or moderate-income, says Elliott.
“These are neighborhoods full of people with talent, determination, and dreams who deserve investment,” she says. “I’ve examined banks’ performance, helped direct their community investments, and now lead an organization that puts bank capital to work financing homes, small businesses, and affordable housing across Michigan. I know how much CRA accountability matters.”
According to OppFund, in fiscal 2024, CRA-motivated bank lenders supplied nearly $6.2 billion — 46% of borrowed capital — to Opportunity Finance Network members.
“Removing a separate community development test for roughly 800 banks risks weakening an incentive that brings investment to communities too often overlooked,” Elliott says. “We need a modern CRA that asks more of our financial system and measures whether people’s needs are being met. My mother purchased her first home at 60. I want more families to have that opportunity, and I don’t want them to have to wait that long.”
The Community Housing Network has worked to empower people to live in affordable homes to help build thriving communities for the past 25 years. CEO and President Kirsten Elliott says through the CRA, they have been able to support homeownership, financial education and services that help move people out of homelessness.
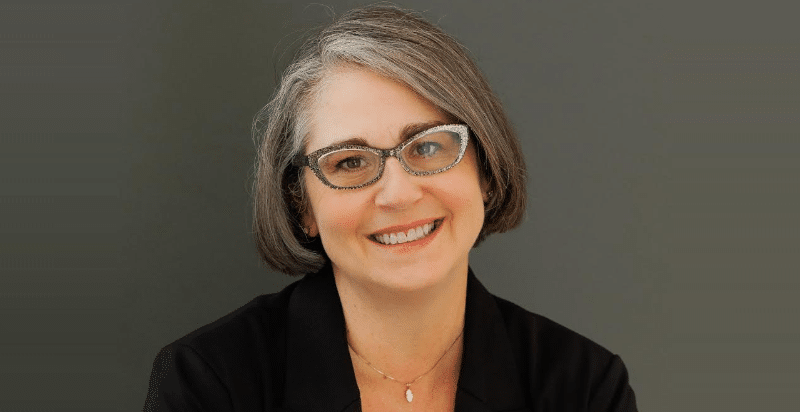
“These investments are more than financial contributions,” she says. “They are partnerships that strengthen communities and create lasting economic opportunity. Proposed changes to the CRA threaten to weaken these partnerships, making it harder for organizations like ours to access capital, develop much-needed affordable housing and serve people facing housing stability. At a time when Michigan is experiencing a significant housing affordability crisis, we should be strengthening the tools that help us address these challenges, not limiting them.”
The comment period closed on Oct. 13, and the Office of the Comptroller of the Currency (OCC) and the Federal Deposit Insurance Corporation (FDIC) are legally required to review every comment submitted, considering alternative proposals, and requests for further analysis before they finalize the rule, says Hill.
While it could take a year or two for these proposed changes to take effect, other things could impact it as well — new administration, lawsuits, etc. The NCRC also submitted a letter to Congress with over 470 organizations’ signatures from across the country.
Related Articles
From Social Worker to Salon Owner, Ky’ronda Tate Brings Luxury and Community to Detroit’s Avenue of Fashion
After years of supporting women through life’s challenges, Ky’ondra Tate is creating a space where Detroiters can feel valued, celebrated and cared for, one manicure at a time.
Minock Park Place provides new affordable senior housing for Grandmont Rosedale neighborhood’s older residents
In the heart of Detroit’s Grandmont Rosedale neighborhood, a 42-unit, mixed-use development has given senior citizens brand-new affordable housing. Minock Park Place was seven years in the making, and marks the first affordable senior housing community in the neighborhood, located at 19505 Grand River Ave. — a vital commercial and cultural artery.
Partner Partner Content From Blueprint to Breakthrough: Tackling Affordable Housing in Detroit
Cass Corridor Neighborhood Development Corporation and Cove Investments and JPMorganChase help neighborhoods—and residents—thrive.